A signed purchase agreement can turn a promising property deal into a binding obligation before the buyer has fully understood what is being acquired, what must be paid, and what risks remain. A property purchase contract review is the point at which those questions should be answered clearly, before deadlines expire and before a dispute has the opportunity to develop.
For a private buyer, the purchase may be the largest financial commitment they make. For a business, property may be central to operations, financing, expansion plans, or a planned acquisition. In both cases, the contract is more than a formality. It allocates risk between the parties and determines what happens if the transaction does not proceed as expected.
What a Property Purchase Contract Review Covers
A contract review examines whether the agreement accurately reflects the commercial deal and whether its terms provide adequate protection for the buyer or seller. The review should not be limited to the purchase price, property description, and closing date. Those items matter, but many of the most significant risks are found in provisions that appear routine.
The first question is simple: what exactly is being sold? The contract should identify the property precisely and make clear what is included in the purchase. That may involve land, buildings, fixtures, parking rights, storage areas, equipment, access rights, or shares in a property-owning entity. If a buyer assumes that a particular asset or right is included, that assumption should be supported by the agreement and the underlying property documentation.
The review should then consider the relationship between the contract and other documents. Title information, surveys, leases, permits, environmental reports, inspection records, financing documents, homeowners association materials, and disclosures can all affect the value and permitted use of the property. A purchase agreement may refer to these materials without explaining their practical consequences. Reading the contract in isolation can therefore create a false sense of security.
Price, Deposits, and Payment Conditions
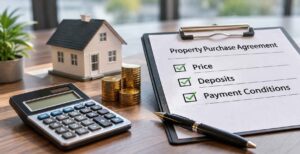
The stated price is only one part of the financial commitment. A careful review considers the deposit, the timing and method of payment, prorations, taxes, transfer costs, title costs, and responsibility for fees connected with financing or registration. The parties should also be clear on whether the price is fixed or subject to adjustment.
Price adjustments are particularly important in commercial transactions. An agreement may provide for adjustments based on rentable area, operating costs, inventory, taxes, utility balances, or other variables. The contract should state how the adjustment is calculated, what documents will be used, who can challenge the calculation, and when any disputed amount must be paid.
Deposit provisions deserve close attention as well. The contract should identify where the funds will be held and under what circumstances they are released. If the buyer cannot complete the purchase because a contractual condition is not satisfied, the agreement should clearly address whether the deposit is returned. A vague provision can turn a failed transaction into a costly disagreement about who is entitled to the money.
Conditions That Protect the Buyer
Contingencies and conditions are often the buyer’s most important protections. They create a defined period in which the buyer can investigate the property and, if necessary, withdraw or require a solution before becoming unconditionally bound.
Common conditions relate to financing, inspections, title, zoning, environmental matters, board approval, and satisfactory review of leases or operating information. The proper conditions depend on the property and the purpose of the acquisition. A buyer purchasing a residence may need adequate time for inspections and loan approval. A company acquiring a warehouse may need confirmation that its intended operations are permitted, that access rights are secure, and that environmental liabilities are understood.
The wording matters as much as the existence of the condition. A condition that is too narrow may not cover the issue that later emerges. A condition with an unrealistic deadline may expire before the buyer receives the necessary information. The agreement should also explain what notice is required to invoke the condition and whether the seller has an opportunity to cure a problem.
Title, Boundaries, and Third-Party Rights
A property can be physically attractive and still carry legal restrictions that undermine its intended value. Easements, rights of way, utility rights, encroachments, restrictive covenants, liens, and leases may affect how the property can be used, developed, financed, or sold in the future.
A review should distinguish between matters a buyer is willing to accept and matters that must be resolved before closing. For example, a utility easement may be manageable, while an access easement that allows others to cross a key development area may materially change the deal. The contract should specify what title objections can be raised, the deadline for raising them, and the seller’s obligation, if any, to remove or address them.
Where the property is leased, the buyer should understand each lease rather than relying solely on a rent schedule. Key points include the lease term, renewal rights, rent increases, security deposits, maintenance obligations, assignment rights, defaults, concessions, and any tenant options to purchase or terminate. A lease can be an asset, but it can also limit flexibility long after closing.
Representations, Disclosures, and Due Diligence
Seller representations are statements of fact that the buyer may rely upon when deciding whether to proceed. They may address ownership, authority to sell, compliance with laws, litigation, environmental conditions, leases, permits, service contracts, and undisclosed defects.
The practical value of a representation depends on its wording and the remedy available if it proves inaccurate. Broad language may be narrowed by knowledge qualifiers, materiality thresholds, disclosure schedules, survival periods, and liability caps. For example, a seller may only represent what it has actual knowledge of, or the contract may require losses to exceed a specified amount before a claim can be made.
This does not mean that every transaction requires extensive warranties from the seller. A seller may reasonably resist open-ended liability, especially in a competitive market or an arms-length commercial sale. The goal is to identify the risks that matter most and ensure they are addressed through due diligence, contract protections, price adjustments, insurance, or another workable solution.
Default, Remedies, and the Cost of a Failed Closing
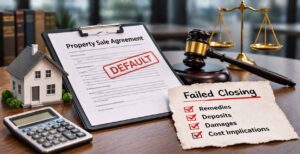
No party enters a transaction expecting a failed closing, but the contract should address that possibility with precision. What happens if the buyer does not close? What happens if the seller cannot deliver the property as promised? Is the deposit the sole remedy, or can the non-defaulting party seek additional damages or require performance?
Remedy provisions can substantially shift bargaining power. A buyer may want the right to recover the deposit and pursue damages if the seller breaches. In some circumstances, the buyer may also need the right to seek specific performance, meaning a court order requiring the seller to complete the transfer. A seller, on the other hand, may seek to limit its exposure by making return of the deposit the buyer’s exclusive remedy.
Neither approach is automatically right. The appropriate balance depends on the property, the market, the parties’ negotiating position, and the practical harm that a failed transaction would cause. What should be avoided is accepting a remedy clause without understanding its effect until after a problem occurs.
Why Timing Matters in a Property Purchase Contract Review
The most useful review occurs before the contract is signed, not after the buyer has waived contingencies or committed a nonrefundable deposit. Early legal input makes it possible to negotiate language, coordinate due diligence, and align the agreement with the client’s commercial objectives.
That said, a review can still add value after signing. If concerns arise during the due diligence period, prompt advice can help determine whether the issue triggers a contractual right, whether notice must be given, and whether a renegotiation is possible. Deadlines in real estate contracts are often strict, and waiting for informal discussions to resolve a concern can jeopardize important rights.
At Advantage Advokatbyrå, contract advice is approached as a practical part of the transaction, not an academic exercise. The focus is on identifying the terms that may affect the client’s risk, options, and ability to complete the deal on acceptable terms.
Before committing to a property purchase, make sure the agreement reflects more than the property you hope to acquire. It should also reflect the risks you are prepared to take, the protections you need, and the path available if the transaction does not go according to plan.