A claim denial can turn a covered loss into an immediate business problem. Property remains damaged, operations may be interrupted, and the insurer’s explanation can appear final even when key facts have not been fully considered. Insurance claim disputes are often resolved not by arguing louder, but by identifying the policy language, evidence, and procedural deadlines that will determine the outcome.
For businesses and individuals alike, the first response matters. A rushed acceptance of a denial, an incomplete proof of loss, or an informal conversation that is never documented can make a later challenge harder than it needs to be. The practical objective is to protect your position early while keeping the path to a commercial resolution open.
Why insurance claim disputes arise
Most disputes do not begin with a simple refusal to pay. They begin with disagreement about what happened, what the policy covers, how much the loss is worth, or whether the insured complied with policy conditions.
An insurer may take the position that an exclusion applies, that the damage existed before the reported event, or that the claimed loss falls outside the policy’s coverage period. In a business interruption claim, the parties may agree that a covered event occurred but strongly disagree about lost revenue, saved expenses, and the period of restoration. In a liability matter, the dispute may concern whether the insurer has a duty to defend, rather than the ultimate value of the underlying lawsuit.
Policy wording is central, but it is rarely the only issue. Insurance claims are built on records: photographs, maintenance logs, contracts, invoices, financial statements, expert reports, witness accounts, and communications with adjusters. Where the evidence is incomplete or inconsistent, the insurer may have more room to question causation or valuation.
There is also a difference between a legitimate coverage disagreement and an inadequate claims-handling process. Delays without clear explanation, shifting reasons for denial, a failure to investigate relevant information, or a valuation that ignores material evidence may warrant closer scrutiny. The appropriate response depends on the policy, the governing law, and the facts of the loss.
Read the policy before responding to the denial
A denial letter is not the final word. It is the insurer’s stated position at a particular point in the claim. The next step is to compare that position against the full policy, including declarations, endorsements, definitions, conditions, exclusions, and amendments.
This review should answer several practical questions. What coverage was purchased? Is the insurer relying on an exclusion, a condition, or a definition? Does an endorsement change the general wording? What notice, cooperation, documentation, appraisal, mediation, arbitration, or lawsuit deadlines apply?
Small wording differences can be decisive. For example, coverage for direct physical loss may raise different issues from coverage for loss caused by a specifically listed peril. A “vacancy,” “wear and tear,” “intentional acts,” or “professional services” exclusion may appear broad, but its application depends on the actual facts and the policy’s definitions.
Do not rely solely on a certificate of insurance, a renewal summary, or an adjuster’s description of coverage. Those documents may be useful, but the policy itself controls. If portions are missing, request a complete certified copy promptly.
Watch the clock
Deadlines can be as consequential as the coverage language. Policies often require prompt notice, a sworn proof of loss, cooperation with an investigation, or participation in an appraisal process. Statutes may also limit the time to bring a legal claim.
Meeting a deadline does not mean conceding the insurer’s position. A proof of loss, for example, can preserve a claim while expressly reserving disagreement over the amount owed. If a deadline is unclear, treat it as urgent. Waiting for the insurer to “finish its review” may be risky if a contractual limitation period continues to run.
Build the record that supports your claim
The strongest response to an insurer is usually organized evidence, not a broad accusation that the decision is unfair. The record should show the event, the resulting damage or loss, the connection between them, and the financial impact.
For a property loss, preserve damaged items where feasible until they have been inspected. Take dated photographs and video, retain repair estimates and invoices, and keep records of mitigation efforts. If emergency repairs are necessary to prevent further damage, document the condition before, during, and after the work whenever possible.
For a commercial claim, financial documentation is equally important. Prior sales trends, budgets, customer orders, payroll records, tax returns, inventory data, and correspondence about canceled work can all help establish loss. A company seeking business interruption coverage should be prepared to explain its calculation in a way that distinguishes actual loss from assumptions about future performance.
Keep communication with the insurer in writing whenever practical. After a phone call, send a brief confirmation of what was discussed, what information was requested, and what will happen next. This creates a reliable timeline and reduces the risk of later disagreement about statements or commitments.
How to challenge an insurer’s position effectively
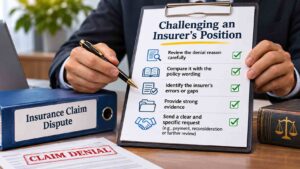
A useful challenge is specific. It should identify the insurer’s stated reason for denial or underpayment, quote the relevant policy provision, explain why the provision does not support that outcome, and attach the evidence that matters.
A well-prepared demand or reconsideration letter often addresses four points: the relevant facts, the policy language, the insurer’s errors, and the requested action. Depending on the claim, that action may be payment of a defined amount, withdrawal of a denial, a supplemental investigation, appointment of an independent expert, or a meeting to discuss resolution.
Avoid overstating the case. If some portion of the loss may not be covered, separate it from the portion that is supported by the policy. Credibility matters in negotiations and in court. A clear, measured position makes it easier to identify what is genuinely in dispute.
Appraisal, mediation, arbitration, or litigation?
The right process depends on the disagreement. Appraisal can be useful when coverage is accepted but the parties dispute the amount of property damage. It may be less helpful when the real issue is whether the policy covers the loss at all.
Mediation can give both parties flexibility, particularly where a business relationship, timing, or confidentiality matters. Arbitration may be required under certain policies and can be faster than court, though appeal rights are often limited. Litigation may be necessary when the insurer refuses to apply coverage, important legal interpretation is at stake, or negotiations have reached a genuine impasse.
Each option involves trade-offs. Early settlement can reduce cost and uncertainty, but settling before the damages are properly documented may leave significant value on the table. Litigation can create leverage and compel evidence through formal discovery, but it requires time, resources, and a disciplined case strategy.
When legal counsel adds value
Legal support is particularly valuable when the loss is substantial, the policy contains layered coverage issues, the insurer has reserved its rights, or a denial affects business continuity. Counsel can assess the policy as a whole, preserve deadlines, coordinate with experts, and present the claim in a form that is ready for negotiation or formal dispute resolution.
For business owners, insurance disputes also need to be viewed alongside contractual obligations to customers, lenders, landlords, and employees. A delayed payment may trigger consequences far beyond the claim file. A strategic legal approach considers those operational pressures while pursuing the available insurance recovery.
Advantage works with clients facing contested claims and related commercial disputes by combining careful legal analysis with a practical focus on the next decision. The goal is not to prolong a conflict unnecessarily. It is to place the client in the strongest position to obtain a fair and timely outcome.
If an insurer has denied, delayed, or reduced your claim, preserve the policy, correspondence, and evidence before taking the next step. A focused review early in the process can turn an unclear dispute into a defined case with a workable path forward.