A deal can look attractive in the boardroom and become far more complicated once the diligence process begins. M&A market trends are changing not only which businesses attract buyers, but also how transactions are priced, financed, documented, and completed. For owners considering a sale and buyers pursuing growth, the central question is no longer simply whether to transact. It is whether the deal structure properly reflects the risks that exist today.
The market remains selective. High-quality companies with recurring revenue, clear market positions, experienced management, and credible growth plans can still generate strong interest. Businesses with unclear earnings, customer concentration, unresolved employment matters, or weak contract discipline often face a slower process and more demanding terms. Preparation has become a meaningful source of value.
M&A Market Trends Put Quality Under Scrutiny
Buyers are spending more time testing the durability of earnings. A healthy revenue figure is not enough if it depends on a small number of customers, one-time projects, unusually favorable pricing, or a founder whose relationships have not been transferred to the wider organization.
This does not mean every company must be perfect before entering a sale process. It does mean that management should be able to explain the story behind the numbers. Why did margins change? Which customers are committed under enforceable agreements? What portion of revenue is recurring? Are there operational improvements that can be achieved after closing, or are they merely assumptions used to support the valuation?
For sellers, a well-organized data room is therefore more than an administrative task. It is an opportunity to show that the business is managed with discipline. Financial records, material agreements, intellectual property documentation, corporate records, employment arrangements, permits, disputes, and insurance matters should be reviewed before a buyer identifies the gaps.
For buyers, deeper scrutiny should remain commercially focused. Not every irregularity warrants a price reduction or a broad indemnity. The practical issue is whether a finding could affect value, delay closing, create a liability, or limit the buyer’s intended plans for the business.
Valuation Is More Than a Multiple
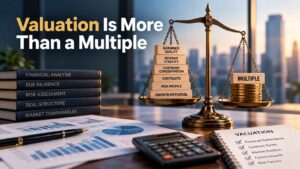
Headline valuation multiples remain useful reference points, but they can be misleading when viewed in isolation. The same industry may contain businesses with materially different risk profiles. A software company with long-term contracts and low churn is not comparable to one dependent on annual renegotiations. A construction-related business with documented change-order processes is different from one carrying disputed project claims.
The result is a greater focus on the bridge between enterprise value and the amount sellers actually receive. Parties need to discuss working capital, net debt, transaction expenses, tax exposure, and any earnout or deferred consideration early. A strong headline price can lose its appeal if the closing accounts mechanism is unclear or if the seller takes on open-ended post-closing exposure.
Earnouts can help close a valuation gap when buyer and seller disagree about future performance. They are not automatically favorable to either side. A seller may gain access to additional consideration, but only if the performance measures are precise and the buyer’s obligations after closing are clearly defined. Questions about budgeting, accounting policies, integration, investment, and decision-making authority can determine whether an earnout is achievable in practice.
Financing Conditions Shape Deal Terms
The availability and cost of capital affect negotiations even where a buyer does not rely entirely on acquisition debt. When financing is expensive or lenders impose tighter conditions, buyers may seek more conservative valuations, increased rollover equity, deferred payments, or stronger protection against unexpected liabilities.
That pressure can also affect timing. A buyer may need longer exclusivity to secure financing or obtain investment committee approval. Sellers, in turn, may want evidence of available funds before granting exclusivity or disclosing highly sensitive information. The right approach depends on the buyer’s profile, the competitive process, and the seller’s need for certainty.
Private equity sponsors continue to play an important role in many markets, particularly where a platform company can make follow-on acquisitions. Strategic buyers may have different advantages: they can offer operational synergies, access to customers, or a long-term home for the business. Neither type of buyer is inherently better. The decisive factors are often certainty of closing, cultural fit, the treatment of management, and the terms attached to the purchase price.
Due Diligence Has Become a Negotiation Tool
Due diligence is often described as an information-gathering exercise. In reality, it is also where the commercial balance of a transaction takes shape. Findings influence price, conditions to closing, indemnities, disclosure schedules, and the work required before completion.
Employment issues are a recurring example. Buyers commonly examine key employee agreements, incentive plans, restrictive covenants, classification questions, workplace policies, and any pending or threatened disputes. If value depends on a specialized team, retention planning should begin before signing. A transaction can be legally completed while still failing commercially if critical employees leave shortly afterward.
Commercial contracts deserve the same attention. Change-of-control clauses, assignment restrictions, termination rights, pricing obligations, exclusivity provisions, and data security commitments may all affect the value of a target company. A contract that appears routine can require customer consent before closing, creating a timing issue that should be identified early.
The most efficient diligence process distinguishes between issues that need remediation and issues that need explanation. Trying to cure every historical imperfection can delay a transaction unnecessarily. Ignoring a material issue can be more costly. Experienced legal and financial advisors help parties determine which path is proportionate to the risk.
Risk Allocation Is Becoming More Deliberate
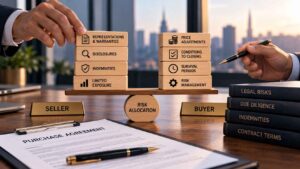
Purchase agreements increasingly reflect a more tailored approach to risk. Buyers want confidence that the information they relied on is accurate. Sellers want a clean exit and protection from claims based on matters the buyer knew about or could reasonably assess.
This is where disclosure becomes central. A disclosure schedule should not be treated as a last-minute attachment. It is a practical record of the business’s known exceptions, obligations, and risks. Clear disclosures can reduce post-closing disputes because they establish what was communicated during the process.
The appropriate package of representations, warranties, indemnities, caps, baskets, and survival periods depends on the transaction. A founder-led sale to a strategic acquirer may require a different balance than a management rollover in a sponsor-backed acquisition. Warranty and indemnity insurance may be useful in some transactions, especially where a seller seeks limited ongoing exposure, but it does not replace careful diligence or precise drafting.
People and Integration Are Deal-Critical
Many deals are signed on financial logic but succeed or fail based on people. Buyers need a credible plan for leadership, employee communication, decision rights, systems, and customer relationships. Sellers should understand how the buyer intends to run the company after closing, particularly where management is expected to remain.
Cultural fit is not a vague concern. It affects retention, integration speed, and customer confidence. A fast-growing entrepreneurial company may struggle inside a highly centralized group if responsibilities change without clear communication. Conversely, a business that needs stronger systems may benefit significantly from a buyer with operational scale and governance experience.
Legal planning supports integration by identifying where approvals, consultation duties, employment transfers, permits, and contractual notices are required. Addressing these points early avoids a common mistake: treating closing as the finish line rather than the start of a demanding operational transition.
What Buyers and Sellers Should Do Now
For sellers, the strongest preparation begins well before a formal process. Review corporate housekeeping, key contracts, employment arrangements, intellectual property ownership, regulatory obligations, and current disputes. Build a clear equity story that is supported by evidence, not optimistic projections alone. If a weakness exists, understand it and decide whether it should be corrected, disclosed, or reflected in the transaction structure.
Buyers should define their non-negotiables before receiving the data room. Is the priority technology, customers, geographic expansion, talent, assets, or market share? That answer determines where diligence time and negotiation leverage should be concentrated. It also prevents teams from becoming absorbed by minor issues while missing a risk that undermines the original investment rationale.
Both sides benefit from involving legal counsel early enough to shape the process rather than merely document an agreed deal. Early advice can help set a realistic timetable, protect confidentiality, anticipate consent requirements, and avoid deal terms that look simple but create unnecessary exposure later.
A well-prepared transaction does not eliminate uncertainty. It gives decision-makers a clear view of the uncertainty they are accepting, the price they are receiving for it, and the protections they need if the facts change. That clarity is often what turns a promising deal into a durable one.